
Salem Home Insurance Quotes: Compare Options for Local Coverage
Finding the right Salem home insurance quotes takes more than just picking the lowest price. You need coverage that actually protects your home and fits your budget.
We at LeDoux Insurance help homeowners navigate their options by breaking down what matters most. This guide walks you through gathering quotes, comparing carriers, and understanding the factors that shape your rates.
What Coverage Do Salem Homeowners Actually Need
If money is owed on a home, then a lender will require homeowners insurance, but Oregon law does not require consumers to have homeowners insurance. This flexibility creates real decisions that affect your financial security. Dwelling coverage in Salem typically ranges from 80 percent to 100 percent of your home’s replacement cost, and this number matters significantly because underinsuring leaves you exposed to substantial out-of-pocket expenses after damage.
The number 100% seems to be not appropriate for this chart. Please use a different chart type.
The National Association of Insurance Commissioners reports that one in five homeowners is underinsured. Salem homeowners face particular risk given Oregon’s exposure to wildfires, windstorms, and occasional flooding in certain neighborhoods. Most carriers recommend getting your home professionally appraised to determine accurate replacement cost rather than guessing based on market value, since construction costs in the Salem area average around 150 to 180 dollars per square foot for standard residential construction.
Dwelling and Personal Property Coverage
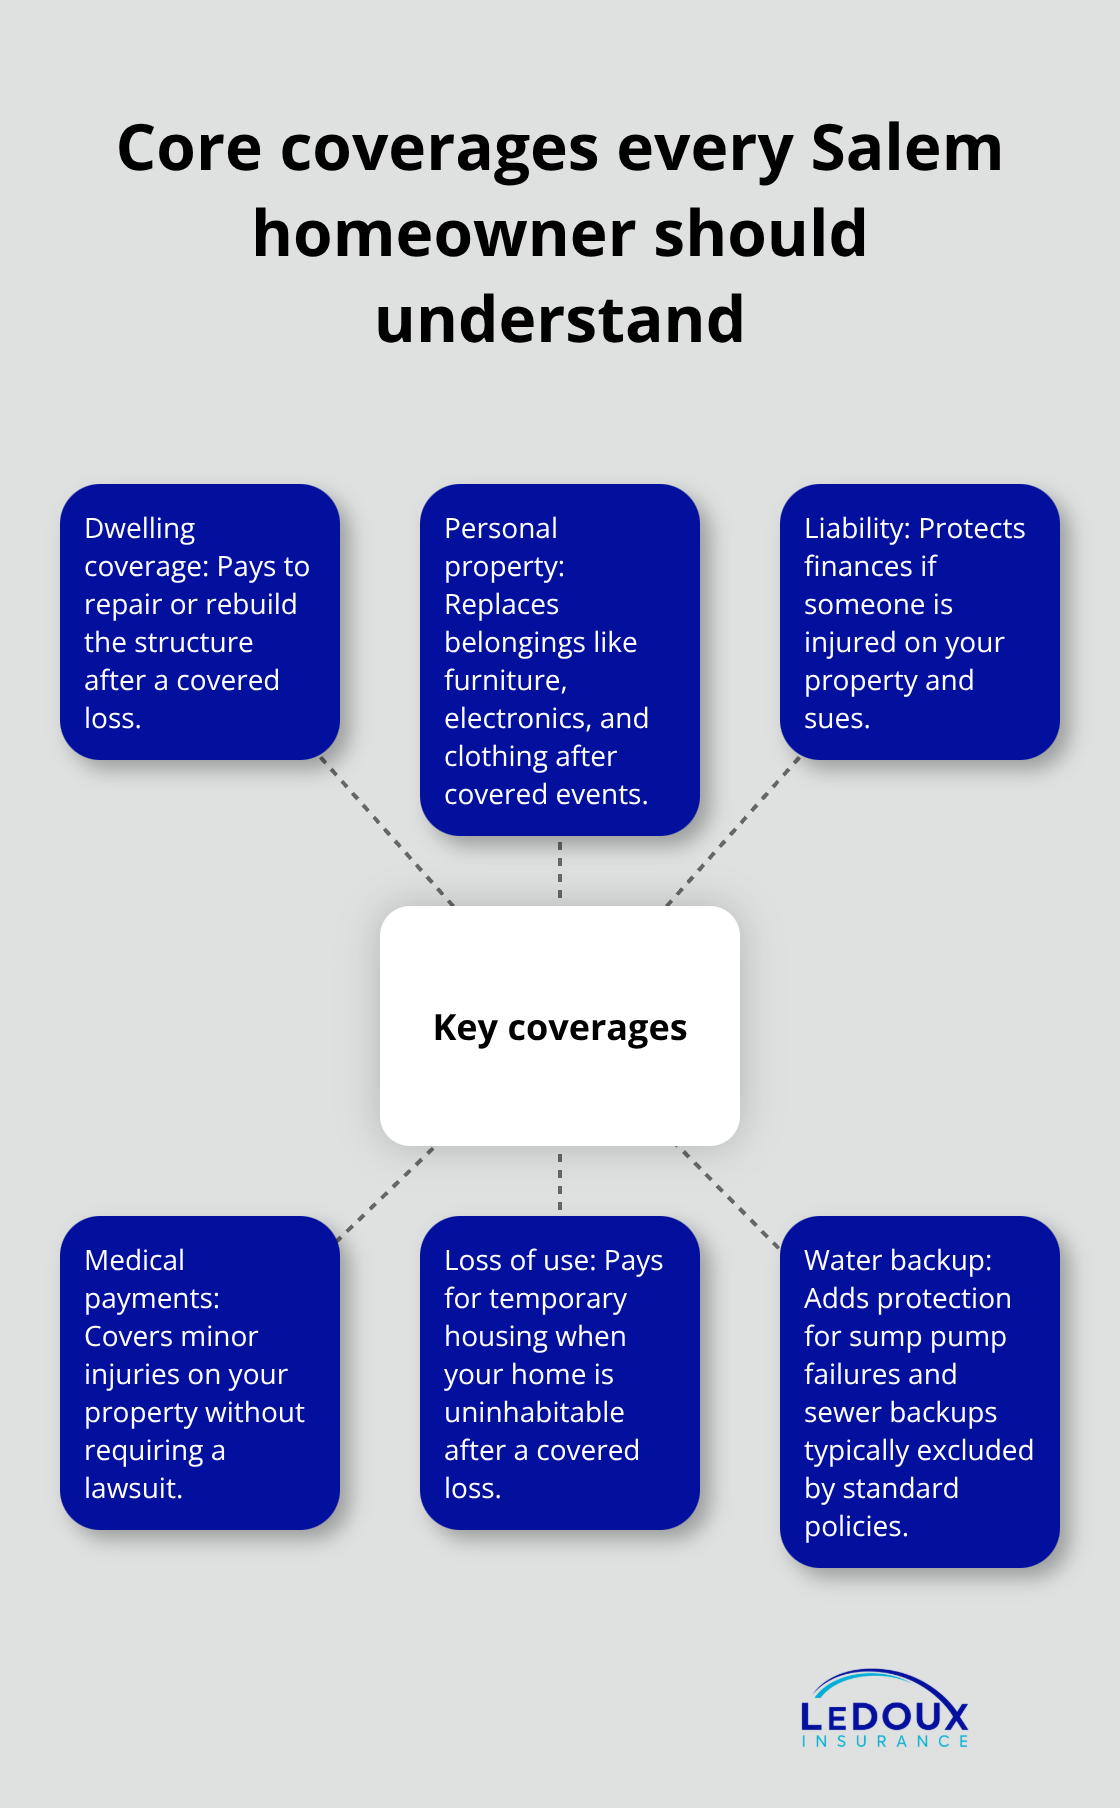
Dwelling coverage pays for structural repairs, but you also need personal property coverage to replace belongings inside your home. Personal property coverage typically covers 50 to 70 percent of your dwelling limit unless you purchase additional endorsements. This protection matters because a single fire or theft can destroy thousands of dollars in household items, furniture, and electronics.
Liability Protection Shields Your Assets
Liability coverage protects you financially if someone is injured on your property and sues. Oregon courts have awarded judgments exceeding 500,000 dollars in premises liability cases, making this protection genuinely important rather than optional. Medical payments coverage handles minor injuries on your property without requiring a lawsuit, and most policies include 1,000 to 5,000 dollars in this protection.
Loss of Use and Water Backup Coverage
Loss of use coverage pays for temporary housing if your home becomes uninhabitable after a covered loss. This matters significantly in Salem’s rental market where temporary housing can cost 1,200 to 1,800 dollars monthly. You should also consider water backup coverage as a separate endorsement since standard policies exclude sump pump failures and municipal sewer backups-events that have affected Salem neighborhoods during heavy rain events.
Understanding these coverage types helps you make informed decisions about protection levels. The next step involves gathering the specific information carriers need to calculate accurate quotes for your situation.
Getting Accurate Quotes for Salem Coverage
Compile Your Home’s Details Before Requesting Quotes
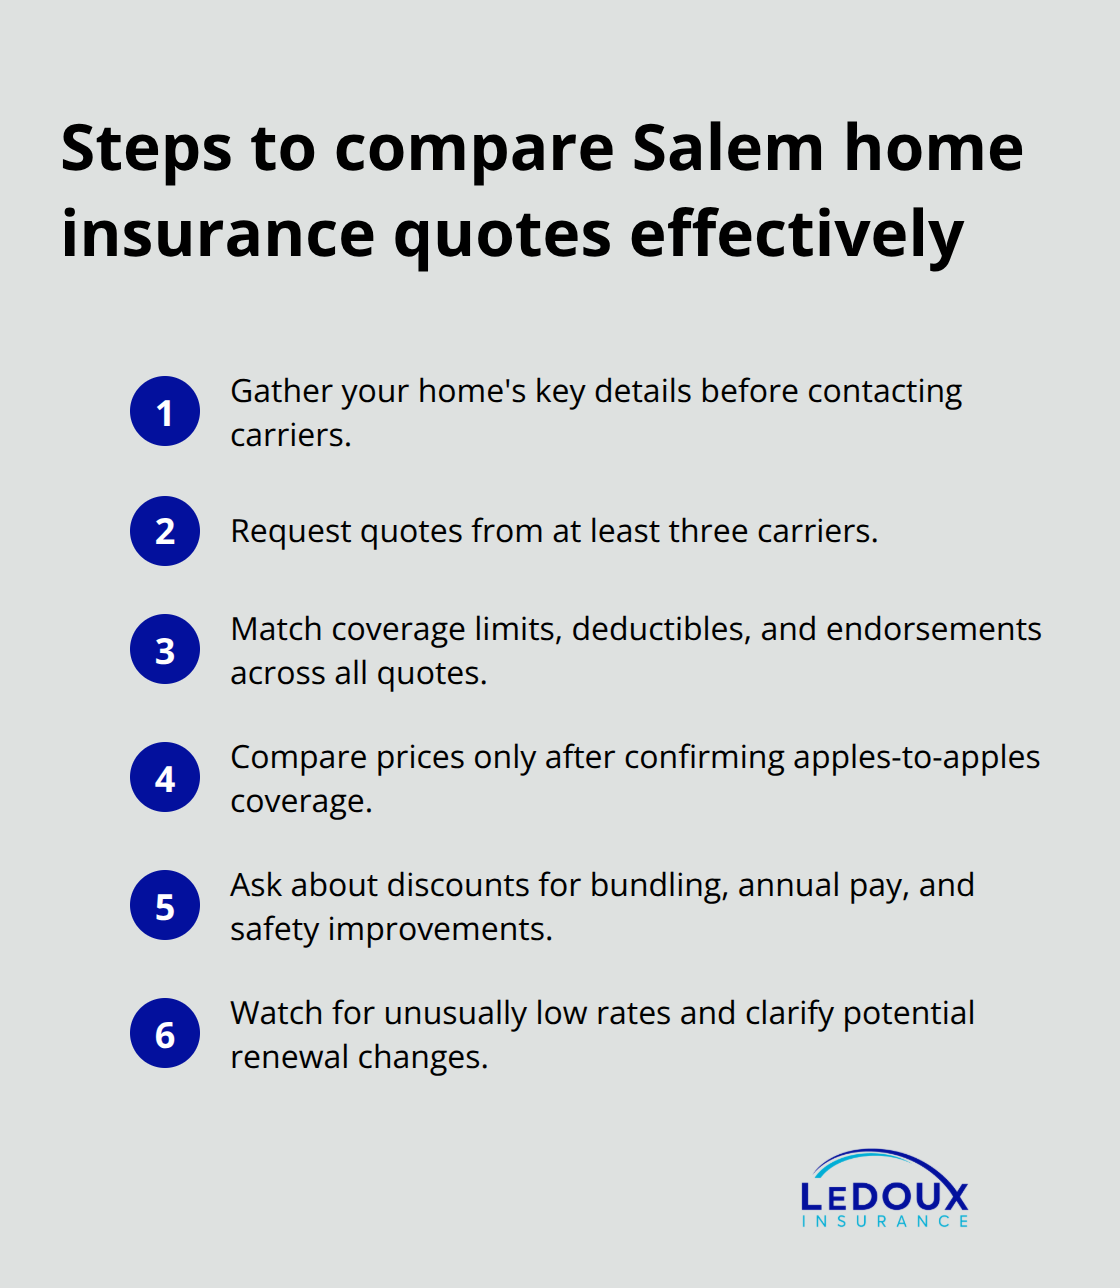
Gathering the right information before contacting carriers saves time and prevents quote delays. Carriers need your home’s square footage, year built, number of stories, roof material, heating system type, and distance from the nearest fire hydrant. Construction details matter because a 1970s home with original wiring and plumbing costs more to insure than a 2015 home with updated systems. You should also have your mortgage lender’s name and loan number ready, along with details about any recent home improvements or major repairs.
The Oregon Department of Consumer and Business Services recommends documenting your home’s condition with photos and a detailed inventory of valuables, which helps establish accurate personal property limits and supports claims if damage occurs. Salem homeowners should also note whether their home has security systems, deadbolts, or fire alarms since these features can reduce premiums by up to 15 percent depending on the carrier.
Request Quotes From Multiple Carriers
Request quotes from at least three carriers rather than settling for one option. Comparing quotes reveals significant price differences because carriers weight risk factors differently, and what costs 1,200 dollars annually with one company might cost 950 dollars with another for identical coverage. This variation means your choice of carrier directly impacts your annual expenses.
Compare Coverage Details, Not Just Price
When reviewing quotes side by side, verify that coverage limits, deductibles, and endorsements match across all options before comparing prices. A cheaper quote with a 2,500 dollar deductible and no water backup coverage differs substantially from a higher quote with a 1,000 dollar deductible and comprehensive water backup protection. The lowest price often masks significant gaps in your actual protection.
Identify Red Flags in Quote Comparisons
Watch for carriers that quote unusually low rates, which often indicate they’ll raise your premium significantly at renewal or deny claims aggressively to offset underpricing. Salem homeowners should also ask each carrier about available discounts for bundling home and auto policies, paying annually instead of monthly, and completing home safety improvements (these can reduce your total cost by 20 to 35 percent across your insurance portfolio).
As you narrow your options based on price and coverage, the factors that shaped those quotes become your next focus-understanding what drives your rates helps you identify opportunities to lower costs while maintaining the protection your home actually needs.
What Drives Your Salem Home Insurance Rates
How Your Home’s Physical Characteristics Shape Costs
Your home’s characteristics directly shape your insurance costs more than most homeowners realize. A 1950s home with knob-and-tube wiring costs significantly more to insure than an identical-sized 2010 home with modern electrical systems because older wiring increases fire risk substantially. Construction type and roofing materials matter equally-a wood-frame home with a composition roof costs more than a brick home with a metal roof because materials affect both damage likelihood and repair expenses.
Your home’s square footage directly influences your premium since larger homes require more materials to rebuild and contain more personal property to protect. Salem carriers calculate premiums by assessing these specific risk factors tied to your property, and accurate documentation prevents either overpriced quotes or undiscovered coverage gaps at claims time.
Location-Based Risk Factors in Salem
Salem’s location within Oregon creates specific risk exposures that carriers price into your quotes. Homes within wildfire zones see premiums 15 to 40 percent higher than properties in lower-risk areas, and this variation increased significantly after the 2020 wildfire season when insurers reassessed Oregon’s exposure. Proximity to flood-prone areas along the Willamette River or Salem’s creek systems raises rates for water damage coverage, and carriers now require elevation certificates for homes in mapped flood zones before quoting.
Your Claims History and Credit Score Impact Rates
Your claims history directly impacts renewal rates-filing even one homeowners claim typically increases your premium by 10 to 20 percent for three years, while multiple claims can result in non-renewal. Credit scores influence premiums because insurance companies view payment behavior as predictive of claims patterns, with poor credit scores sometimes adding 25 to 50 percent to your annual cost.
Actions That Lower Your Rates
Taking action matters here: updating your home’s roof, improving drainage around your foundation, or clearing vegetation near your structure can reduce wildfire risk and sometimes lower your premium by 5 to 15 percent depending on your carrier’s underwriting guidelines. These improvements address the specific risk factors that carriers assess when calculating your rates.
Final Thoughts
Choosing the right coverage for your Salem home requires balancing protection with affordability, and this decision shapes your financial security for years. The coverage limits you select, the deductibles you accept, and the endorsements you add should reflect your home’s actual replacement cost and your ability to handle out-of-pocket expenses after a loss. Underinsuring saves money today but creates devastating exposure tomorrow, while overinsuring wastes premium dollars on protection you don’t need.
Your next step involves requesting Salem home insurance quotes from multiple carriers and comparing them side by side using the framework covered in this guide. Gather your home’s details, request quotes with identical coverage limits and deductibles, and review each quote carefully before making your decision. This process typically takes a few hours but directly impacts your annual costs and the protection your family receives.
We at LeDoux Insurance have served Oregon communities for over 45 years, representing more than 20 top-rated carriers from our Salem office and throughout the state. Our team can gather your home’s information, request quotes from multiple carriers, explain the differences between options, and help you select coverage that actually protects your home without overpaying. The right coverage exists at a price that fits your budget, and starting this process today means your home has proper protection before the next storm, fire, or unexpected loss occurs.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.

